Money in Life Decisions
You don’t have to arrive with the answers. Come ready to question your assumptions, work with the evidence and discover what a different way of thinking — and someone else’s perspective — can reveal.
 Ryna MiFounder, The Wealth School · Former private‑banking CEO · Creator of Existential Portfolio Theory
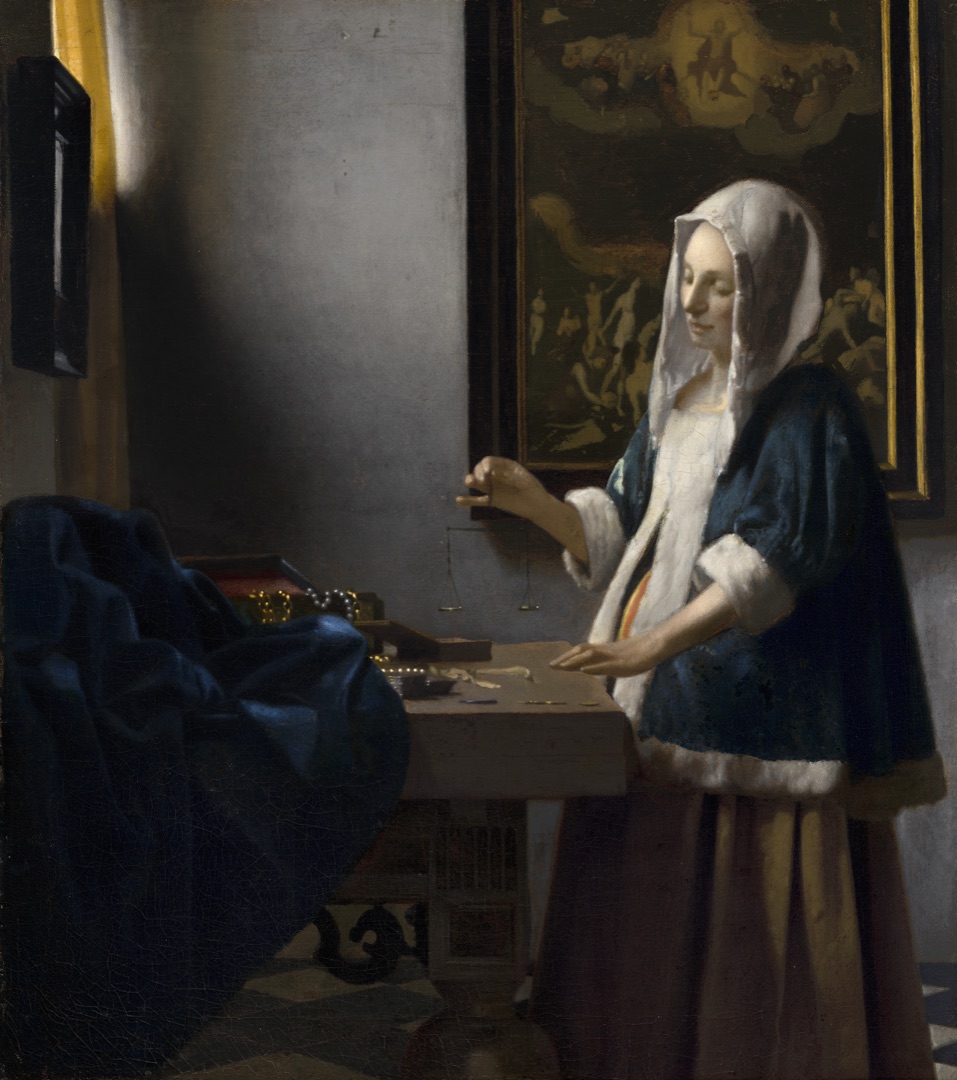
“People always live for ever when there is an annuity to be paid them.”Fanny Dashwood, in Jane Austen’s Sense and Sensibility, 1811, chapter 2
In Jane Austen’s Sense and Sensibility, John Dashwood promises his dying father that he will provide for his stepmother and 3 half-sisters.
At first, he considers giving them £3,000. Then he talks it over with his wife. She questions what he owes them, how much they really need and whether smaller gestures might be enough.
By the end of the conversation, his proposed £3,000 has dwindled to occasional presents of fish and game. And John is satisfied.
Nothing in the women’s circumstances changed during that conversation.
John’s sense of what he owed did.
Is this for you?
Some decisions involve substantial sums. Others involve very little money and just as much consequence.
You don’t need savings, property or investments to join. This conversation is yours, too.
See more. Understand better. Choose for yourself.
If a decision is in front of you
Whether to study further or start earning, take on a mortgage or loan, invest in a business, accept an inheritance or support a parent.
Whatever your starting point
Other good ways to learn about money
You can learn a great deal about money without paying for a course.
Here are 6 free resources we recommend. Some help you understand how money works. Others show how our habits, circumstances and relationships shape the decisions we make with it.
To understand how money works
The Big Three
Stanford Initiative for Financial Decision-Making · questions by Annamaria Lusardi and Olivia Mitchell
Three questions on compound interest, inflation and diversification, asked in financial-literacy surveys around the world.
A quick way to find out what you know, and what you have only assumed.
How Money Smart Are You?
FDIC
14 interactive games on borrowing, debt, housing, saving and spending.
American examples and rules; the habits travel.
YUMO
UBS
Videos, quizzes and short explanations of money and economics, written for young adults starting work.
Swiss, free and published by a bank: worth learning from, and worth remembering who is teaching.
To explore how people make decisions
Saving for Tomorrow, Tomorrow
Shlomo Benartzi · TED
Why it is easy to plan to save next year and hard to start today, and how present bias, loss aversion and inertia shape saving decisions.
An accessible first look at behavioural finance, from one of its practitioners.
The Uber Game
Financial Times
A week as a ride-hailing driver, with bills, fuel and family commitments, deciding each day whether to keep driving.
Shows how financial pressure narrows the choices that follow.
The Evolution of Trust
Nicky Case
Why cooperation holds or breaks down when the same people expect to deal with each other again.
Not about money as such; about why the terms of an agreement are only part of how people behave under it.
Selected by Ryna Mi · links reviewed 7 November 2026
Examining a decision begins before anything is calculated. A decision written two centuries ago shows where.
The Anatomy of a Financial Decision
What are we actually choosing between?
John and his wife consider 3 possibilities: a lump sum, yearly support or occasional gifts. But the women who would receive that support have no say in defining the options.
And how did the smallest offer come to feel reasonable?
Before comparing the options, ask who chose them — and what was left out.
7 questions we use throughout the course
A financial decision changes depending on what you examine. John’s proposed support is no exception.
- 01 · MoneyWhat is it worth?What would £3,000 now, yearly support or occasional gifts be worth to John and to the 4 women?
- 02 · MechanismHow would it work?What would John actually commit to? What, if anything, would bind him to provide the support, and what could he change or withdraw?
- 03 · TimeWhen, and for how long?When would the money arrive? How long might the women need it? What if their needs change over 10 years?
- 04 · RiskWho bears what goes wrong?If John stops providing support, his circumstances change or the women’s needs grow, who bears the consequences?
- 05 · Competing CapitalsWhat else is at stake?Where the women can live, what the daughters can learn, whom they can marry, and how independently they can live.
- 06 · ReversibilityWhat cannot be undone?If the support doesn’t come now, could John make up for it later? Could the women recover the opportunities they lost?
- 07 · SovereigntyWho decides?Who has the authority to decide? Whose wishes and consent matter? Who will live with the consequences but has no voice in the decision?
The 7 questions help us see what the decision involves. They don’t tell John what he ought to do.
What can we conclude?
We can estimate the value of John’s different proposals. We can examine what, if anything, he would be committed to providing.
But the numbers cannot settle what he ought to give. And the women have not been asked what they need or want.
The 7 questions help us examine a decision. The Third Position helps us understand what we can responsibly conclude.
Every working session ends here.
The same scene opens the School’s other 2 Foundational Courses, each with its own question. → The other 2 courses
In Austen’s story, John’s judgement changes as the conversation unfolds. In the working sessions, yours may change when new evidence arrives.
5 decisions we’ll work through together
Each session begins with a financial question people face at different points in life. You’ll work through fictional cases, learn how the financial arrangements work, compare alternatives and reconsider your first conclusions when new evidence arrives.
Open any session to discover the case, what you’ll practise and what changes along the way.
The financial concepts are introduced before you’re asked to use them.
01InvestWhat is worth committing money, time and effort to?Education, career changes, business ideas and the opportunities you give up today for a possible benefit later.Case · Milan’s next 2 years14 or 16 January
Milan’s next 2 years
Milan is 24. He has a bachelor’s degree, some savings and a job offer. He could start earning, study for a further degree, or pursue a shorter qualification while working.
What would studying really cost compared with starting work? How much would he need to earn later to recover that difference — and how certain could he be of doing so?
- Compare money spent or earned in different years at the same point in time.
- Identify which costs genuinely differ between alternatives, including the earnings Milan would give up while studying.
- Calculate how long a possible earnings advantage would take to recover the additional cost.
- Test how the comparison changes when assumptions about pay, costs or timing change.
- Examine an apparently attractive offer for the commitments attached to it.
Opportunity cost · incremental cost · compounding · present value · simple and discounted payback · sensitivity
Guided Exercise 1: Compare 2 commitments at the same valuation date, then calculate 1 consequence for Milan’s later life using the supplied assumptions.
Examine an AI’s comparison against your own work. Has it compared the same alternatives, included the earnings Milan would forgo, and made its assumptions about future pay clear? A correct calculation can still answer the wrong question.
A financial comparison is only useful when the alternatives, timing and assumptions are clear.
02CommitWhat are you really agreeing to when you borrow, buy or sign?Mortgages, rental agreements, loans and guarantees — obligations that can reach far beyond a monthly payment.Case · The larger home · The CHF 1 apartment28 or 30 January
The larger home and the CHF 1 apartment
Case A · The larger home A family wants a larger home. The monthly mortgage payment looks manageable. But will the bank agree to lend? Could the family still afford the arrangement if one income stopped? And what happens when the mortgage terms change?
Educational focus lending · affordability · refinancing
Case B · The CHF 1 apartment Elsewhere, a couple is offered the use of an apartment for CHF 1 a year. The price is almost nothing. The conditions are another matter.
Educational focus ownership · use · conditions
In both cases, the amount paid tells only part of the story.
- Understand how a bank loan works: what interest costs, how amortisation reduces the debt, and what the borrower remains responsible for.
- Distinguish the monthly payment from the bank’s affordability test, and both from what the household can sustain if circumstances change.
- Recalculate the cost of a mortgage when the interest rate or household income changes.
- Distinguish ownership of a property from a contractual right to use it.
- Read an occupation agreement for the rights it grants, the conditions it imposes and who can bring the arrangement to an end.
Credit creation and funding · interest and amortisation · affordability · refinancing · ownership and use
The fixed part of the family’s mortgage comes up for renewal at 4.6%.
- 4.6% renewal rate for the fixed part of the mortgage
The monthly cost changes, but that is not the only question. What can the family renegotiate, what alternatives are actually available, and what would each require them to accept?
Guided Exercise 2: Read the mortgage term sheet and the apartment occupation agreement. Identify the rights, obligations, conditions and missing information in each.
Ask an AI to explain the loan and the bank’s affordability test. Check its calculations against the case documents, then examine whether it has confused what the bank will permit, what the household can afford and what the agreements actually allow.
03RiskWhen does a financial loss become one you cannot come back from?Concentrated investments, money you cannot access, guarantees and fees that accumulate over time.Case · Marguerite’s offer18 or 20 February
Marguerite’s offer
Marguerite has spent years building a company. Now someone offers CHF 42 million to buy it.
But CHF 42 million is the headline price, not a cheque she can deposit. Some money would arrive when the sale closes, some would be held in escrow, and some would come as shares in the buyer’s company that she cannot sell for 36 months.
How much is the offer really worth to her? How much could she actually use? And which risks would still be hers after selling the business?
CHF 42 million headline price
- At closing Part paid at closing.
- In escrow Part held in escrow.
- 36 months Part in buyer’s shares, locked for 36 months.
0.85% a year An adviser proposing a fee of 0.85% a year.
- Distinguish the headline price from money received at closing, conditional payments and shares that cannot yet be sold.
- Examine the value of restricted shares under different scenarios, including what cannot be known from the available evidence.
- Identify the risks Marguerite would still carry after the sale, and which of them she might be able to reduce.
- Calculate how an annual adviser fee accumulates over 1 year and 20 years, including the returns the deducted money might otherwise have earned.
- Examine how the way an adviser is paid can influence what is proposed.
- Distinguish a loss that reduces expected wealth from one that could prevent recovery or close important future choices.
The same questions arise with much smaller sums: an investment you cannot sell, money promised but not yet received, a guarantee you may have to honour, or fees deducted year after year.
Equity · concentration · liquidity · lock-ups · change of control · deferred consideration · expected value and survival · fee drag
The buyer receives a takeover offer. A change-of-control provision in Marguerite’s agreement extends the restriction on her shares.
She expected to be able to sell those shares after 36 months. Now that possibility moves further away.
What changes in her assessment of the sale? Which risks could she have anticipated, reduced or negotiated differently — and which remain beyond her control?
Guided Exercise 3: Compare 2 ways of structuring the sale, reproduce the adviser-fee calculation and identify what becomes difficult or impossible to reverse.
You receive an AI-generated analysis of the case. Find 1 material error, unsupported assumption or unjustified conclusion. Explain why it matters, and identify the evidence or calculation needed to correct it.
04Receive & TransferWhat arrives with what you receive, and what does it cost to say yes, no or nothing?Inheritances, gifts and family-company interests that may come with debts, conditions or deadlines.Case · The inheritance with a guarantee4 or 6 March
The inheritance with a guarantee
An estate includes a flat with a mortgage, a 15% interest in a company that cannot be freely transferred, and a guarantee the deceased signed for a relative’s business loan.
- The flat with a mortgage
- 15% company interest transfer restricted
- The guarantee extent of exposure uncertain
There are assets of potential value. But what are they worth after the obligations attached to them? What could the heirs actually do with what they receive? And how far might the guarantee reach?
The heirs must examine their options while some important facts are still uncertain — and the deadlines may not wait.
- Distinguish assets from liabilities, established debts from possible exposures, and the apparent value of an inheritance from what it may ultimately be worth.
- Distinguish ownership of a company interest from control over the company and the ability to transfer or sell that interest.
- Read a notary’s explanation of procedures and fees alongside a proposal that also involves a financial product.
- Identify which questions need qualified legal advice and which financial comparisons can be made from the available evidence.
The legal rules belong to the country of the case. The course teaches you to recognise and examine these questions, not to give inheritance or trust advice.
Rights and liabilities · ownership and control · estate responses under Swiss law · buy-back provisions · the cost of inaction
An inventory and a letter from the bank reveal more about the estate and how far the guarantee may reach.
Does this change which response the heirs should examine most closely? What is now established, what remains uncertain, and what must they clarify before the relevant deadlines?
Examine an AI’s account of the estate. Has it overlooked a liability, misunderstood a legal distinction or deadline, or treated a possible exposure as an established debt? Identify what must be checked against the documents or confirmed by a qualified professional.
05Preserve & ProvideHow do you provide for the future without losing choices you may need later?Your own later years, care for a parent, and savings that may need to last longer or serve more people than expected.Case · Ruth’s 5 options · Sami’s family18 or 20 March
Ruth’s 5 options and Sami’s family
Ruth, 71 Ruth is 71. She and her family are considering 5 ways to provide for the years ahead. Each has different financial consequences. But before comparing them, they need to understand what Ruth herself wants.
Sami, 49 Sami is 49 and self-employed. He has CHF 210,000 in savings and no occupational pension. His mother, 83, lives in Marseille and needs care. His sister lives in Lyon.
How much can Sami contribute to his mother’s care while keeping enough for his own later life? What should he plan for, what might he be responsible for, and what does he still need to establish?
- Understand how inflation reduces what money can buy, and how longevity changes the amount needed for later life and care.
- Examine why the order of investment gains and losses matters when someone is drawing regularly on savings.
- Compare Ruth’s 5 options over time and identify which assumptions make the greatest difference to the financial result.
- Distinguish the financial cost of an option from whether it meets Ruth’s wishes.
- For Sami, distinguish money available today from savings intended for later life, and examine what different levels of support could mean for both.
- Identify where family responsibilities, financial capacity and possible legal obligations require separate examination.
Inflation and real value · longevity · liquidity · sequence of returns · family support obligations · currency exposure
Ruth Ruth chooses an option her family had not expected. The financial comparisons may still be correct, but they must now be considered in the light of what she wants.
Sami Later, Sami’s mother is admitted to hospital again. Her care needs may have changed, and so may the family’s options.
What needs recalculating? What needs to be established? And whose wishes and decisions must shape what happens next?
In the session’s judgement lab, examine an AI-assisted financial projection alongside the established facts. Which figures and assumptions can you verify? What remains uncertain? And where does the conclusion require human judgement?
Prepare for your final independent decision brief. You’ll receive a new fictional case, not covered in the working sessions, and examine it without AI.
Each case prepares you to examine a decision you haven’t encountered before.
From guided cases to independent work
Financial intelligence makes more of a decision visible, without pretending to make the decision for you.
- Guided financial learning
- Practising across cases
- Independent examination
- Individual assessment
Across 5 working sessions, you’ll examine financial arrangements through their figures, documents, alternatives and consequences. The concepts are introduced with worked examples before you use them. You’ll test calculations and conclusions against new evidence and other people’s interpretations.
The final challenge is to apply what you’ve learnt to a case you haven’t encountered before.
5 practices you’ll use across the course
- 1
Compare the alternatives
Work through financial comparisons: what actually differs between the options, what each costs over time, and how the answer changes when an assumption changes.
Practise using compounding, present value, payback and sensitivity, including recognising when the available information doesn’t yet support a reliable calculation.
- 2
Read the terms
Examine agreements for their rights, obligations, fees, conditions and restrictions.
Distinguish money available now from value that depends on future events. Learn what to look for in the documents, what questions to ask, and where specialist advice is needed.
- 3
Test what could go wrong
Look beyond the expected financial result.
Examine concentration, liquidity, dependence on other people or events, and what a loss could mean for the choices still available afterwards.
- 4
Account for what the figures leave out
Consider how a financial commitment affects time, health, relationships and future freedom.
Examine who defined the alternatives, whose interests are involved, who has the authority to decide and who will live with the consequences.
- 5
Form and test a human judgement
Distinguish established facts from assumptions and uncertainty.
Question how the options were framed, how incentives and your own first impressions might influence the analysis, and whether the evidence supports your conclusion. Practise changing that conclusion when new facts warrant it — or explaining why a decision cannot yet be made.
You learn to use AI to examine supplied financial cases, verify its calculations, challenge its assumptions and conclusions, and develop financial judgements you can defend independently.
Your independent decision brief
At the end of the course, you receive a fictional decision that no working session has covered. You examine it independently, without AI, and produce a 1-page decision brief.
Your brief:
- Sets out what is known, what is assumed, what matters most and what remains uncertain.
- Includes the calculations the available information permits.
- Examines credible alternatives, their consequences and whose decision each part is.
- Reconsiders the initial analysis when a second piece of evidence arrives.
- Reaches a supported conclusion, or identifies what must be established before a conclusion can be reached.
An individual written review
Ryna reviews your brief against 5 published criteria:
- Mechanism and figures
- Evidence
- Alternatives and interdependence
- Authority
- Judgement
The calculations that matter must be correct under the assumptions stated, or the brief must explain why a reliable calculation cannot yet be made.
The review establishes what your work demonstrates against these criteria in this unfamiliar case. It does not claim that you have mastered every financial mechanism or can independently resolve every financial decision.
Savings of CHF 210,000 held liquid; pillar 3a CHF 48,000 locked to retirement grounds; no occupational pension.
Fund the gap from savings (EUR 1,800 a month); fund it with his sister; defer his own provision; apply for the French assistance first.
First-pillar entitlements unknown; the mother’s own preference not yet asked; the support obligation under French law unverified; CHF/EUR over 10 years.
A decade of his working life committed; the sister’s position; what happens to Sami’s own retirement provision as his savings support his mother’s care.
The mother decides where she lives; the siblings decide what each gives; the French assistance decides nothing until applied for.
Withheld, conditional: establish the mother’s preference and the assistance first.
How your work is recognised
- Participation
- Attending the working sessions.
- Completion
- Attending the working sessions and submitting the guided work, including the final independent brief. Recorded in a Statement of Completion.
- Demonstrated competence
- An independent brief that meets the financial-integrity requirement and the published assessment criteria, confirmed in the individual written review. This recognition concerns demonstrated performance against the course’s assessment standard. It is not a general professional qualification or a claim of competence across all financial situations.
No grade, ranking or accredited award. Legal, tax and pension questions appear where the cases require them; the course does not qualify participants as specialists in these fields.
You write the final brief alone. Most of the preparation happens with others, in a group of up to 12.
How you’ll learn
You’ll work in a live group of up to 12 people. Some will be encountering these financial questions for the first time. Others may have spent years working with banks, advisers, businesses or investments.
Everyone examines the same cases, but not everyone needs the same preparation or the same questions.
The class brings those different perspectives together, while your individual work and learning resources are adapted to where you’re starting from.
Who joins the class
Beginning your financial life
You may be deciding about further study, work, borrowing or a first long commitment, and would rather understand a contract, a loan or a trade-off before you sign than afterwards.
Deciding for yourself or a family
You may be weighing a home, a career change, a business, care for a relative or provision for later life, and want to examine the financial consequences more carefully.
Long experienced with wealth and advice
You may have spent years with banks, advisers, businesses or family wealth, and want to look harder at familiar arrangements: how they work, what they assume, whose interests they serve and what they leave out.
Everyone works with the same cases and towards the same assessment standard. The preparation and further resources allow participants to approach that work from different starting points.
How the learning works
Before each working session · Prepare
- Around 6–10 pages of essential reading, with a worked example.
- 3 short questions to check your understanding, without grading.
- The financial concepts needed for the case are introduced before you are asked to use them.
You do not need to arrive knowing how to discount a future payment, calculate mortgage costs or interpret a business-sale agreement.
Together · Investigate
- Each working session lasts 90 minutes and takes place live on Zoom, in a group of up to 12.
- Ryna explains the relevant financial mechanisms. You then examine the case with other participants, work through its figures and documents, and compare interpretations.
- You work in pairs: one person examines the document, the other works with the figures, and you exchange roles.
- Partway through the case, new evidence arrives. You reconsider which conclusions still hold, which have changed and what remains uncertain.
Between sessions · Develop your own understanding
- You complete guided work between sessions, with the option to work through the calculations yourself or use supplied figures while concentrating on the reasoning.
- During the teaching period, Ryna checks in with you individually each week in a short private exchange about your progress and questions.
- From the established course material, she selects further practice or resources according to what you need: another explanation, additional practice or a more demanding line of inquiry.
- Your group can continue discussing the cases through the course chat.
- Each teaching week also includes 30 minutes of shared live question time with Ryna.
Everyone follows the same 5-session curriculum and works towards the same assessment standard.
Your learning library
The same financial question can lead different people in different directions. Your learning doesn’t have to stop where the shared session ends.
Chosen for you
Ryna curates a personal collection of books, articles, podcasts, films, lectures, interactive resources and other material to help you explore further.
Her selections take account of your financial understanding, the languages you read in, the cultural and institutional contexts familiar to you, and the interests or life questions you choose to share.
Your questions and individual check-ins help shape what she recommends next. You may need another explanation of a financial mechanism, or you may be ready to explore its implications in economics, psychology, law, history or other fields.
Built by your group
Your group develops a shared collection from its discussions and discoveries: a source that challenges an assumption, a film that changes how someone sees a decision, an article that answers a question raised in class.
Ryna helps select and organise these contributions, so the collection remains useful to the learning rather than becoming another stream of links.
What is required? The essential preparation for each session is clearly marked. Everything else in the libraries is there to explore at your own pace.
Both libraries remain yours to access for life. They bring together resources you can return to as your questions, circumstances and interests change.
What makes the room work
The class asks for preparation, curiosity and a willingness to examine an interpretation that differs from your own.
You don’t need to agree with anyone. You do need to be ready to question your reasoning, explain what supports it and reconsider when the evidence changes.
People with different experience often notice different things in the same case.
An experienced participant can be wrong about a clause. A beginner can ask the question everyone else overlooked.
Objections are taken seriously, errors are corrected, and conclusions must stand up to the evidence. Every case is fictional, and nobody is asked to discuss their own finances.
Course materials you keep Your final decision brief and its written review · the 7 questions and the Third Position on 1 card · case documents and worked examples
The work asks for your attention and preparation. Before you commit, you should know exactly what it involves — including the time, tuition and support available afterwards.
What you commit to, and what you receive
You’ll join 5 live working sessions, prepare between meetings and work towards an independent decision brief.
Ryna teaches the financial mechanisms, guides the case work, checks in with you individually and reviews your final brief. You’ll learn alongside a group of up to 12 people, with opportunities to return to your questions after the live sessions have ended.
The tuition is CHF 1,000. Here’s what the work involves, what the School provides and what remains available afterwards.
Money in Life Decisions · Foundational Class
CHF 1,000Payment in instalments available.
No prior financial experience or particular level of wealth is required. You’ll be able to review the enrolment and payment terms before committing to a paid place.
- Format
- Live online · English · 18+
- Working sessions
- 5 sessions of 90 minutes.
- Dates
- January–March 2027.
- Groups
- Up to 12 people per group.
- Choose
- Thursday or Saturday.
- Individual guidance
- Weekly during the teaching period, followed by educational check-ins available on request through December 2027.
- Your learning libraries
- 2 curated collections, accessible for life.
Choose your class
The course runs twice in 2027. Both classes work through the same 5 sessions, cases and assessment, in a Thursday or a Saturday group.
Founding Cohort · January 2027
Thursday group 18:00–19:30 Geneva14 January · 28 January · 18 February · 4 March · 18 March
| 01 · Invest | 14 January |
|---|---|
| 02 · Commit | 28 January |
| 03 · Risk | 18 February |
| 04 · Receive & Transfer | 4 March |
| 05 · Preserve & Provide | 18 March |
Saturday group 13:30–15:00 Geneva16 January · 30 January · 20 February · 6 March · 20 March
| 01 · Invest | 16 January |
|---|---|
| 02 · Commit | 30 January |
| 03 · Risk | 20 February |
| 04 · Receive & Transfer | 6 March |
| 05 · Preserve & Provide | 20 March |
Opening and closing assemblies 15:00–16:00 GenevaSaturday 9 January · Thursday 25 March 2027
Opening assembly: 9 January 2027. Closing assembly: 25 March 2027. These are shared with the School’s other 2 Foundational Courses and are additional to the 5 working sessions.
Times in London, New York and Abu Dhabi
| Location | Thursday | Saturday |
|---|---|---|
| Geneva | 18:00–19:30 | 13:30–15:00 |
| London | 17:00–18:30 | 12:30–14:00 |
| New York · sessions 01–04 | 12:00–13:30 | 07:30–09:00 |
| New York · session 05 | 13:00–14:30 | 08:30–10:00 |
| Abu Dhabi | 21:00–22:30 | 16:30–18:00 |
New York times change in March because the United States moves its clocks forward before Europe does.
May Class 2027
Thursday group 18:00–19:30 Geneva29 April · 13 May · 27 May · 10 June · 24 June
| 01 · Invest | 29 April |
|---|---|
| 02 · Commit | 13 May |
| 03 · Risk | 27 May |
| 04 · Receive & Transfer | 10 June |
| 05 · Preserve & Provide | 24 June |
Saturday group 13:30–15:00 Geneva1 May · 22 May · 29 May · 12 June · 26 JuneMoved: session 02 to Saturday 22 May
| 01 · Invest | 1 May |
|---|---|
| 02 · Commit | 22 May |
| 03 · Risk | 29 May |
| 04 · Receive & Transfer | 12 June |
| 05 · Preserve & Provide | 26 June |
Opening and closing assemblies 15:00–16:00 GenevaSaturday 24 April · Thursday 1 July 2027
Opening assembly: 24 April 2027. Closing assembly: 1 July 2027. These are shared with the School’s other 2 Foundational Courses and are additional to the 5 working sessions.
Times in London, New York and Abu Dhabi
| Location | Thursday | Saturday |
|---|---|---|
| Geneva | 18:00–19:30 | 13:30–15:00 |
| London | 17:00–18:30 | 12:30–14:00 |
| New York | 12:00–13:30 | 07:30–09:00 |
| Abu Dhabi | 20:00–21:30 | 15:30–17:00 |
What the course asks of you
You don’t need to know finance already or own investments or property.
You do need to make time for the work: preparing for the cases, examining unfamiliar financial arrangements, testing your reasoning and being willing to reconsider a conclusion when the evidence changes.
The course is built around participation in an investigation, rather than listening to someone else’s answers.
Your time
- The 5 working sessions total 7.5 live hours.
- You’ll also need time for the essential reading, guided exercises and independent brief.
- The opening and closing assemblies, individual check-ins and shared faculty question sessions are additional parts of the experience.
What the School provides
During the Foundational Class · January–March 2027
- 5 live working sessions of 90 minutes on Zoom, with teaching, case work and a short break.
- Essential reading and worked examples before each session.
- Weekly individual educational check-ins with Ryna, with practice and resources selected for your progress.
- 30 minutes of shared live question time with Ryna each teaching week.
- Your group’s course chat.
- An independent final decision brief, with an individual written review.
- An opening assembly on 9 January and a closing assembly on 25 March, shared with the School’s other 2 Foundational Courses.
What continues after March
The live working sessions end in March, but your connection with the course doesn’t end there.
Through 31 December 2027
- Your group’s course chat remains open.
- Individual educational check-ins with Ryna remain available on request.
- You can continue asking questions, returning to the material and developing your understanding beyond the live sessions.
Your learning libraries · For life
Both curated libraries remain yours to access for life.
Your personally curated learning library and the collection developed with your group remain accessible to you for life.
They bring together sources and references you can return to as your circumstances and questions change.
Before you apply
This course is for people willing to work with fictional financial decisions, calculations, agreements and different interpretations.
It does not provide personalised investment recommendations, professional certification or answers to your own legal and financial arrangements.
- Language and setting
- The course is taught in English, with participants joining from different countries. Several cases use Swiss banking and inheritance arrangements; another concerns family responsibilities across Switzerland and France. The financial methods can be applied beyond these settings. Legal rules and financial conventions differ by country, and the elements specific to a jurisdiction are identified. No knowledge of Swiss law is required.
- Privacy and access
- The cases are fictional. Nobody is asked to disclose their own finances or enter personal financial information into an AI tool. Live discussions are not recorded. No paid AI subscription is required. Zoom requirements and access arrangements are provided with the enrolment information.
- If you miss a working session
- Teaching notes and case materials remain available. Where the other group has space, joining that week’s session may be possible, but cannot be guaranteed. Live discussions are not recorded.
- Scope of the course
- The course teaches a method for examining financial decisions using fictional cases. It does not provide investment selection, portfolio construction, tax planning, pension-product recommendations, specialist valuation, legal drafting or personalised financial advice. The faculty member does not review or recommend decisions concerning participants’ own financial arrangements.
Applying to join the class
The class brings together people with different levels of financial experience, in groups of up to 12.
You don’t need to demonstrate existing financial expertise or hold any particular assets to join.
Full enrolment, tuition-payment, instalment, cancellation and withdrawal terms are available before you commit to a paid place.
This course examines how money works inside a decision. The School’s other 2 Foundational Courses explore what those decisions mean across a life and between the people who share it.
Before you apply
Still have a question?
Do I need to know finance already?
You don’t need a finance qualification, professional experience or investments of your own. But this is a working course, not a comprehensive introduction to finance.
If you’re starting with little financial knowledge, we strongly recommend exploring the free introductory resources in Chapter 01 before the course begins.
You’ll also receive essential reading and worked examples before each session. Secondary-school arithmetic is sufficient, but you should be prepared to study and practise between meetings.
What if I already have substantial financial experience?
The financial mechanisms are taught so everyone has a common starting point. But the work goes further: who defined the alternatives, how assumptions, biases and incentives influence our reasoning, what risks we might overlook, and what even a correct calculation cannot decide.
Your experience brings another perspective to the room — one that can be questioned and tested alongside everyone else’s.
Can I bring questions from my own financial life?
Of course. You’re welcome to ask questions arising from your experience or use a real situation as an example.
We can explore the relevant financial mechanisms, possible alternatives and questions worth investigating. But we won’t assess your personal financial arrangements or recommend what you should do.
You’re never required to disclose personal financial information.
What if I miss a working session?
You’ll receive the teaching notes and case materials. If the other group has space, you may be able to join it that week, though this isn’t guaranteed.
Live discussions aren’t recorded.
Other ways to join the conversation
Come to a free Open Class
The Wealth School also holds free, live conversations about questions that wealth raises in our lives and relationships.
The other 2 Foundational Courses
Money in Life Decisions is 1 of the School’s 3 Foundational Courses. Each stands on its own.
All 3 begin with John Dashwood’s promise in Sense and Sensibility, but approach the same situation through a different question.
Wealth Across a Life
How do decisions change the wealth of a life?
Through the School’s 9 Life Capitals, explore how different forms of wealth develop, interact and change across a lifetime.
In Austen’s story, what might John’s decision mean for the women’s opportunities, independence and lives in the years that follow?
Wealth in Family Life
What happens when wealth is shared, discussed or disputed between people?
Explore how families understand their responsibilities, talk about wealth and make decisions that affect one another.
In Austen’s story, who decides what the father’s promise means, and whose understanding counts?
The 3 courses share an opening assembly on 9 January and a closing assembly on 25 March 2027, but each can be taken independently.
For the decision in front of you, and the ones still to come
Money in Life Decisions ·
Thank you. Your place is confirmed.
The confirmation is on its way to your email. If it has not arrived within a few minutes, please check your spam folder.
What happens next
- Your confirmation email, now
- Your Zoom details, before
- The opening assembly, , Geneva time
- Your first working session, , Geneva time
January–March 2027 · Live online · 5 working sessions · Up to 12 per group · CHF 1,000